Bajaj Housing Finance Stock Analysis: Long-Term Investment Outlook After Record IPO Demand
Bajaj Housing Finance Stock Analysis: Long-Term Investment Outlook After Record IPO Demand
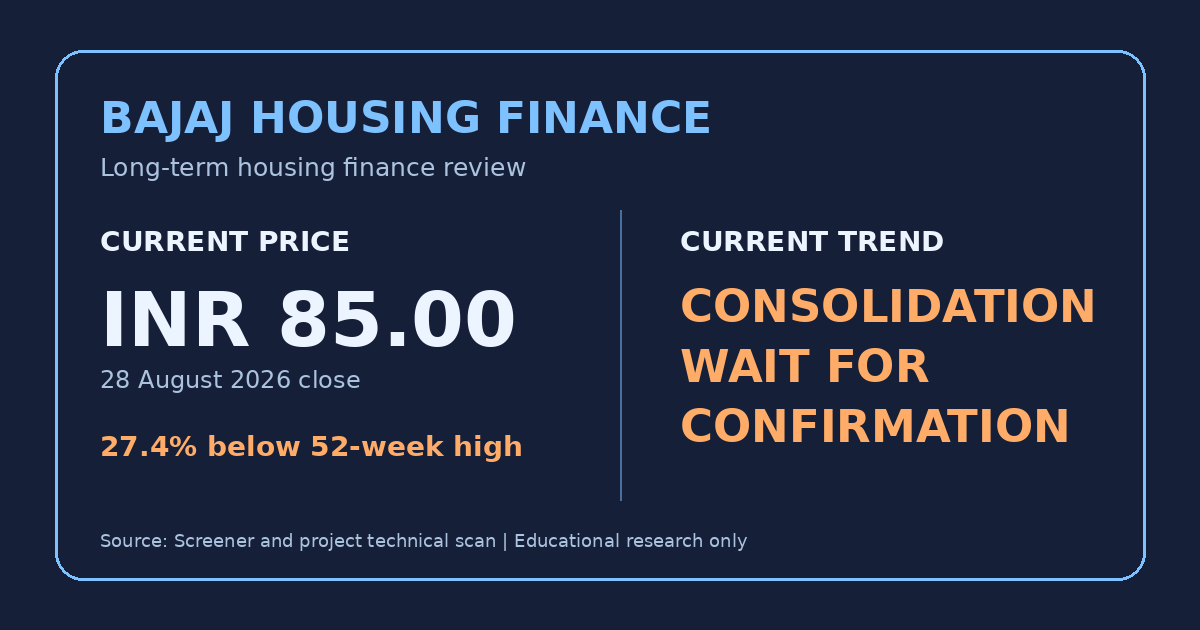
Market data reference: 28 August 2026 close, ₹85.00. Educational research, not investment advice.
IPO Demand: Strong Interest, Not a Current Buy Signal
Coverage of the Bajaj Housing Finance IPO reported exceptional demand, including around 89 lakh applications and ₹3.2 lakh crore of bids. IPO demand shows initial market attention, but it does not determine current valuation or future returns.
Business Quality
Bajaj Housing Finance is a non-deposit-taking HFC and Bajaj Finance subsidiary. It provides home loans, loans against property, developer finance, commercial-property finance and lease-rental discounting. Screener cites AUM of ₹1,33,412Cr as of December 2025, up 23% year over year.
| Metric | Reading | Interpretation |
|---|---|---|
| Market cap | ~₹70,794Cr | Large HFC with meaningful growth expectations. |
| Trailing P/E | ~26.4x | Requires sustained AUM growth and credit quality. |
| ROE | ~12.7% | Solid but needs improvement for a premium re-rating. |
| Revenue growth | ~19.6% | Constructive mortgage-finance growth. |
| Promoter holding | 86.7% | Strong Bajaj-group ownership; lower public float. |
Current Chart: Consolidation, Not Confirmation
- ₹85 is 27.4% below the ₹117 52-week high.
- Price is below the 20/50/100/200-day averages: ₹85.15 / ₹86.38 / ₹86.23 / ₹88.85.
- RSI is 48.2. MACD has improved slightly but remains below zero.
- Recovery confirmation begins above the ₹85-₹86 cluster; longer-term trend repair needs a sustained move above ₹88.85.
Recent Developments
- ₹750Cr secured NCD private placement was allotted on 20 August 2026, maturing in August 2031.
- CRISIL ESG assigned a “Strong” ESG 69 rating on 11 August 2026.
- For an HFC, monitor AUM growth, NIM, funding cost, gross NPA, net NPA and credit cost instead of applying industrial-company debt metrics.
Long-Term Plan
- Do not buy only because the share is below the IPO-period excitement or 52-week high.
- A cautious initial allocation is more defensible after the share holds above ₹85-₹86 with improved volume.
- Add only after a sustained move above ₹88.85 and results confirm AUM growth, margin and asset quality.
- Reassess on a decisive break below ₹72.65, the 52-week low area.
Risks
- Interest-rate and funding-cost pressure.
- Housing and real-estate-cycle slowdown.
- Asset-quality deterioration or rising credit costs.
- Valuation compression if growth disappoints.
Bottom Line
Bajaj Housing Finance is a quality long-term housing-finance franchise, but its chart has not confirmed a recovery. A staged approach tied to price confirmation and quarterly credit-quality data is more prudent than an all-in entry.
Sources
Educational research only. Verify current price, results and risk tolerance before investing.
Comments
Post a Comment