Tata Technologies Stock Analysis: Long-Term Investment Outlook and Price Levels
Tata Technologies Stock Analysis: Long-Term Investment Outlook and Price Levels
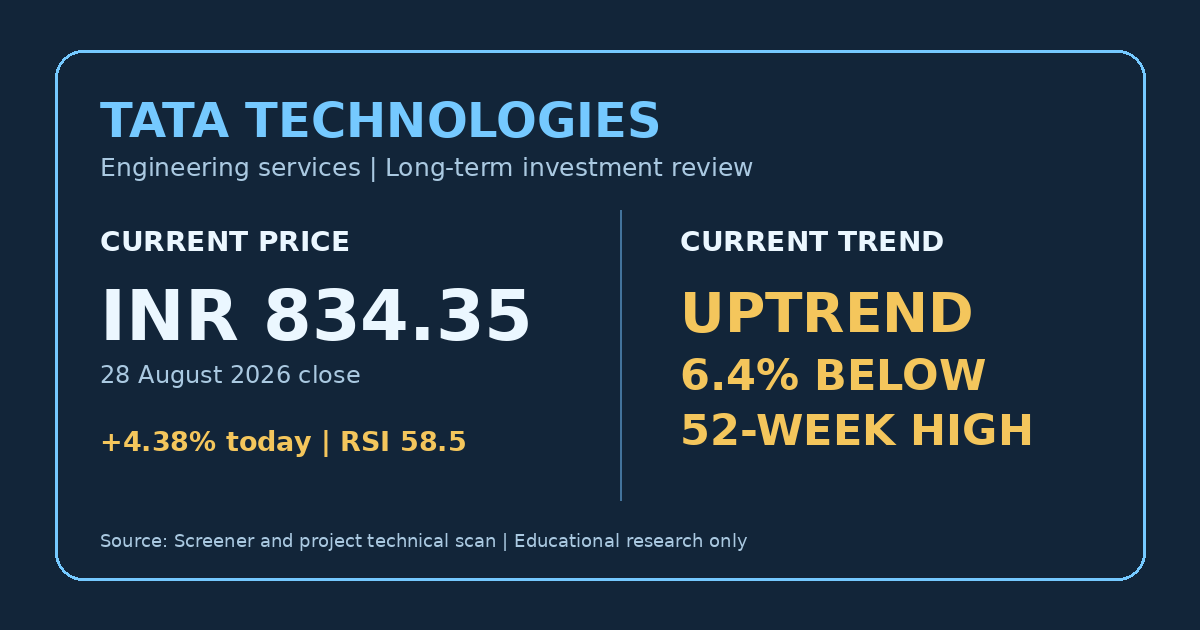
Market data reference: 28 August 2026 close, ₹834.35. Educational research, not investment advice.
What Tata Technologies Does
Tata Technologies is a global engineering, research and development, and digital-solutions company serving automotive, aerospace, and industrial clients. It provides product design, simulation, testing, embedded systems, enterprise software, and digital transformation services. Services contribute about 77% of business and technology solutions about 23%.
Current Fundamental Snapshot
| Metric | Reading | Interpretation |
|---|---|---|
| Price | ₹834.35 | 6.4% below ₹891 52-week high. |
| Market cap | ~₹33,879Cr | Mid-sized engineering-services company. |
| P/E | ~52.1x | Premium valuation requiring sustained growth. |
| ROCE / ROE | 20.9% / 16.3% | Healthy returns on capital. |
| Five-year sales/profit CAGR | 18% / 21% | Strong historical growth record. |
Latest Quarterly Results
| Metric | Jun 2025 | Jun 2026 | Change |
|---|---|---|---|
| Sales | ₹1,244Cr | ₹1,665Cr | +33.8% |
| Operating profit | ₹200Cr | ₹267Cr | +33.5% |
| Operating margin | 16% | 16% | Stable |
| Net profit | ₹170Cr | ₹181Cr | +6.5% |
Revenue and operating profit grew strongly, but net profit grew more slowly. Earnings quality and conversion of growth into EPS are important for the valuation.
Technical Analysis
- Price is above the 20/50/100/200-day averages: ₹821.77 / ₹767.02 / ₹708.64 / ₹660.81.
- RSI is 58.5, constructive but not overbought.
- The latest session rose 4.38% on 1.08x volume.
- MACD remains below its signal, so short-term momentum confirmation is incomplete.
- Support: ₹821-₹822 first; ₹767 stronger 50-DMA support. Resistance: ₹839.70 and ₹891.
Growth Drivers
- Electric-vehicle and software-defined-vehicle engineering demand.
- Product-lifecycle-management and digital-engineering services.
- Tata Group credibility and large industrial customer relationships.
- Potential operating leverage as revenue expands.
Risks
- P/E near 52x leaves little room for execution misses.
- Automotive clients may delay programs in weak demand cycles.
- FY26 consolidated profit declined despite revenue growth.
- FY26 borrowings rose to ₹938Cr from ₹237Cr; monitor leverage and acquisitions.
- The company previously clarified that a Japanese OEM program was already disclosed and that a volume spike had no undisclosed material event behind it.
Long-Term Plan
- Existing holders can retain while price holds above the 20/50-day averages and margins remain stable.
- New investors should avoid chasing a sharp move near the 52-week high.
- Prefer a controlled pullback toward ₹821-₹822 that holds, or a high-volume close above ₹891.
- Reassess below ₹767 or after two quarters of revenue, margin, and PAT deterioration.
Bottom Line
Tata Technologies has a credible long-term engineering and automotive-digitisation story with a constructive chart, but the valuation is demanding. Staggered buying on pullbacks or confirmed breakouts is more prudent than an all-in purchase at ₹834.35.
Sources
Educational research only. Verify current price, filings, results, valuation, and your own risk tolerance before investing.
Comments
Post a Comment